Buying a home can be worthwhile when it meets your daily needs, fits your budget, and gives you flexibility about when to move again. Most owners in a recent national survey felt good about their purchase, but that finding cannot tell you whether a particular home is right for you. For buyers in Valrico, the useful goal is a purchase you can comfortably live with after closing.
Start by asking what would make you want to leave. A difficult commute, an unsuitable layout, or more upkeep than you want can undermine the value of an otherwise attractive purchase. Those issues deserve attention before you decide how much to offer.
Separate your requirements from improvements you could make gradually. Paint and light fixtures are different decisions from needing another bedroom or accepting a location that does not work for your routine. Visit at the times you would normally travel and think through how you would use the rooms, storage, and outdoor space.
Then test your timeline. If a job change or another move is likely within a few years, compare buying with a realistic rental option. Purchasing and selling both involve expenses, so a short ownership period can make the financial outcome more sensitive to prices and transaction costs.
A useful question is: Would this home still meet your needs if your next move happened later than expected? You do not need to predict your whole future, but you should understand which compromises could force an early sale.
Long ownership periods have historically given many buyers opportunities to build equity. The Federal Housing Finance Agency’s Q2 2026 report documents national and state price changes using its seasonally adjusted, purchase-only index. From Q1 1991 through Q2 2026, the national increase was approximately 336%, while Florida’s was approximately 447%.

Those are cumulative changes over roughly 35 years, measured in dollars without adjusting for inflation. They describe single-family house-price trends, rather than an individual owner’s investment return. Financing, maintenance, taxes, insurance, and transaction expenses all affect the financial result.
Over the 5 years ending in Q2 2026, the same index recorded a 33.4% national increase and a 37.5% increase in Florida. The shorter window helps explain why an owner’s purchase date matters, even within a broader upward trend.

Neither map establishes the appreciation of a Valrico home or a condominium. A property’s condition and competing local sales require their own review. For the separate question of what might happen next, our article on interpreting home-price forecasts explains how to use projections without making them the foundation of your purchase.
In NerdWallet’s September 2026 financial regrets study, 74% of Americans who had purchased their current home said they were glad they made that financial decision. Another 13% felt OK about it, 10% had mixed feelings, and 3% regretted it.
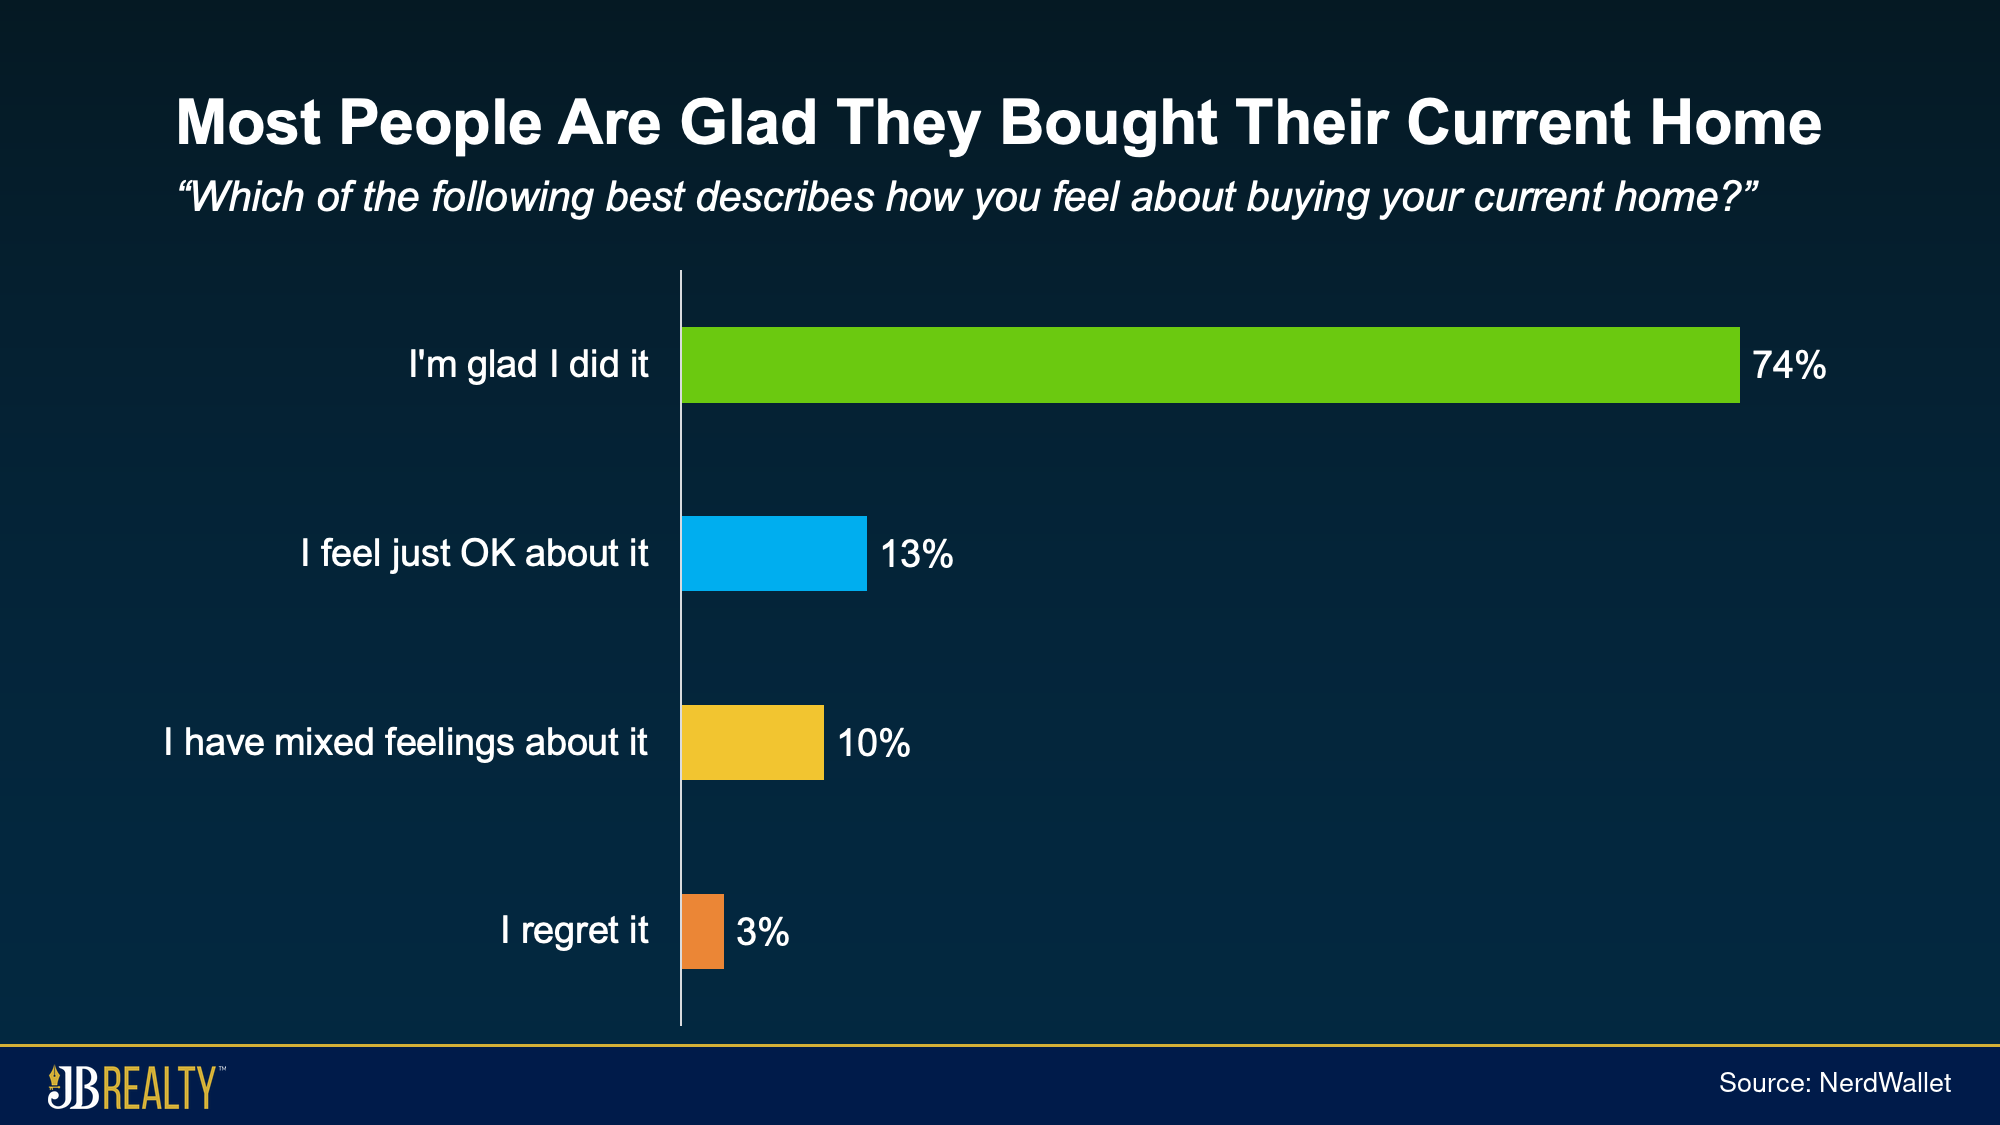
The Harris Poll conducted the survey online from August 4–6, 2026, among 2,086 U.S. adults overall. The home-purchase results concern the relevant subgroup, and they are not limited to people who bought recently. They also do not measure satisfaction specifically in Hillsborough County.
The finding offers perspective if uncertainty has made you assume buyers usually regret their decision. It does not establish why respondents were satisfied or prove that appreciation caused their positive feelings. Your own decision still needs a workable home, budget, and ownership plan.
Before committing, separate the lender’s approval amount from the monthly spending level you want. Include the mortgage payment, property taxes, insurance, and applicable association charges, then leave room for maintenance and your other priorities. Ask the lender to explain which payment components can change.
One local budgeting mistake is treating the seller’s current property-tax bill as your future bill. The Hillsborough County Property Appraiser explains that a seller’s capped assessment remains only through the purchase year, with reassessment at market value the following year. Obtain an estimate for your ownership and confirm any exemptions or portability benefits that may apply.
Keep cash available after closing for repairs and unexpected expenses. A purchase that depends on an immediate refinance, a raise, or rapid appreciation needs another look. Our guide to comparing mortgage offers and purchase costs can help you review the payment and upfront cash together.
Equity is your home’s value minus the outstanding loans secured by it. Paying down mortgage principal can increase equity even when the property’s value stays unchanged. Interest payments do not reduce that principal balance.
Consider a hypothetical $360,000 purchase with $72,000 down and a $288,000 mortgage. If the loan balance later falls to $280,000 while the home remains worth $360,000, equity would be $80,000. If the value instead fell to $340,000, equity would be $60,000 despite the principal reduction.
Neither amount equals profit or the cash you would receive from selling. Selling expenses and other obligations can reduce the proceeds. Treat equity as one part of your financial picture while keeping enough accessible savings to manage ownership.
The survey describes how respondents felt about a past decision. It cannot determine whether your income, savings, housing needs, or local choices support buying now. A comfortable purchase should work with the financing and expenses you can verify today.
That figure describes the national index’s change over the 5 years ending in Q2 2026. It is historical data, not a forecast. An individual property can rise by a different amount, remain flat, or lose value.
There is no universal ownership period that guarantees buying will outperform renting. Compare your likely timeline, purchase and resale expenses, financing, maintenance, and a realistic rental alternative. If you may need to move soon, flexibility deserves extra weight.
You can increase equity by reducing principal on an amortizing mortgage while the home’s value stays unchanged. Your loan terms determine how payments are divided between principal and interest. A decline in value can offset principal payments, and equity does not account for all ownership costs.
Through our homebuying guidance, we can help you compare the homes you are considering against your daily needs and likely time in the property. Ask us to review those tradeoffs alongside your lender’s payment estimate before you choose an offer price.