You can influence the mortgage offer you receive by caring for your credit, comparing lenders and loan structures, and examining builder rate incentives. The rate alone does not tell you which home is affordable. For a purchase in Riverview or Ruskin, compare the full monthly payment and cash needed to close, including property taxes, insurance, and any HOA or CDD charges.
Mortgage rates can change while you search for a home. A daily 30-year fixed-rate series traces several rises and falls between January and September 2026. Its September reading is higher than its January reading, with several reversals in between.

That movement is a reason to ask for current quotes for the property you want to buy. A national average or a daily rate chart cannot account for your credit, down payment, loan program, lender, and the terms available when you apply. It also cannot tell you where rates will go next month. Build a plan around a payment you can manage under the terms offered now.
Two lenders can quote different rates, fees, and closing costs for the same buyer. Give each lender the same purchase price, down payment, loan type, property type, and expected closing date, then ask for quotes close together in time. Otherwise, differences in assumptions or market timing may make one offer look better than it is.
The Consumer Financial Protection Bureau's Loan Estimate comparison guide explains how to compare the interest rate, monthly principal and interest, mortgage insurance, lender charges, credits, and cash to close. Ask whether the quoted rate requires discount points, which are an upfront cost paid to lower the rate. Compare the annual percentage rate, or APR, as another measure of borrowing cost, while remembering that it does not replace a review of the payment and loan terms.
Check the rate-lock status too. A quote may be locked for a stated period or may still change. Ask the lender when a lock expires, what an extension could cost, and whether the closing date for the home you are considering fits that schedule.
Your credit profile can affect the rate and loan options available to you. Start by checking your credit reports for mistakes, paying bills on time, and discussing existing balances with a lender. The CFPB's guidance on mortgage credit scores explains that the score you see in a consumer app may differ from the score used in mortgage lending.
Ask the lender to identify which changes might actually help your application before moving large amounts of money or paying off an account. A payment that reduces debt could change your loan options, but it also reduces the cash you have for closing and reserves. Avoid opening new credit accounts during the mortgage process without talking with your lender.
Conventional, FHA, VA, and USDA loans have different eligibility rules and costs. A lender can show which programs fit your finances and the property. Ask for the monthly payment, mortgage insurance or program charges when applicable, and cash to close under each realistic option.
The loan term changes the tradeoff. A shorter term may be offered at a lower interest rate but usually requires a higher monthly payment because you repay the balance faster. An adjustable-rate loan may offer a different initial rate than a fixed-rate loan, but its rate and payment can change later. Have the lender show the payment under the actual terms, including what could happen after an introductory period.
The comparison should start with your own limits: the monthly amount you can carry comfortably and the cash you want to keep after closing. A slightly lower rate has limited value if the loan requires more upfront spending than your budget allows.
Builder financing deserves a look alongside resale homes. A 2026 Q2 comparison reports an average mortgage rate of 6.47% for buyers of existing homes and 5.85% for buyers of newly built homes. Those are averages for different groups of buyers, not a rate promise for a particular property.
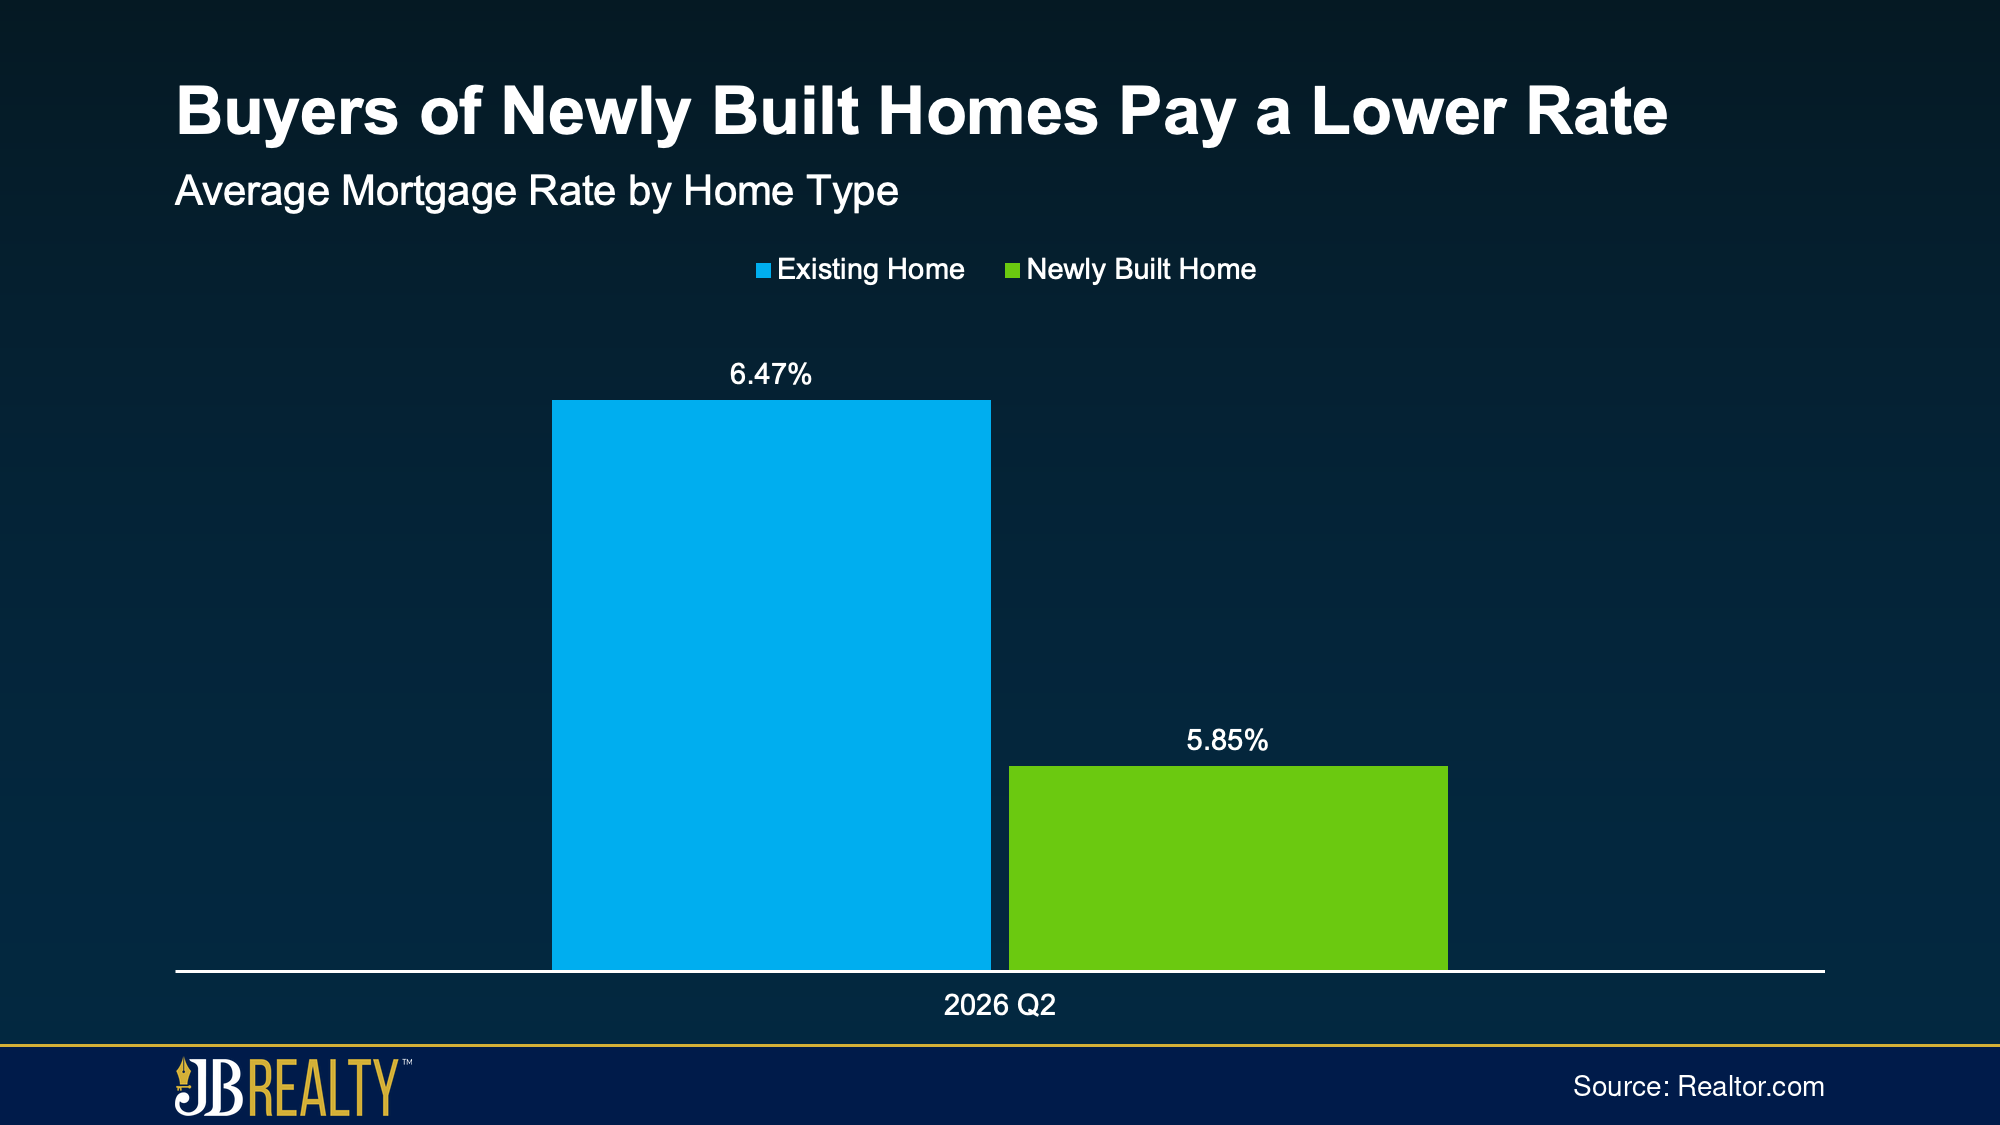
When a builder advertises a rate, ask whether it is a permanent rate for the loan or a temporary reduction in the early payments. Find out whether the offer requires the builder's preferred lender, what points or fees apply, and whether the same home could instead qualify for a price reduction or closing cost credit. Our guide to new-construction costs and incentives explains how to compare those choices.
Then price the actual home, not the advertisement. A new home in Ruskin and a resale in Riverview may differ in purchase price, lot charges, insurance, property taxes, HOA or CDD fees, and what is included at closing. Ask lenders to estimate the full payment and cash to close for each specific property. If an incentive reduces payments temporarily, confirm the payment after it ends and decide whether that amount still fits your budget.
It may give you access to better pricing or more loan options, but a specific improvement does not guarantee a particular rate. Ask a lender which credit information will be used and whether a proposed change would affect your loan offer.
Lenders may have different pricing, fees, points, and credits, and quotes made on different days can reflect changing market rates. Request comparable Loan Estimates using the same loan amount, program, property, and timing before deciding.
It may come with eligibility conditions, a preferred lender requirement, upfront costs, or a temporary payment reduction. Compare the Loan Estimate, purchase price, total payment, and cash to close with another lender and a comparable resale.
A temporary buydown reduces payments for a limited initial period; the payment then rises to the amount based on the loan's stated terms. A lower fixed rate applies under the fixed loan terms, often with an upfront cost if discount points are involved. Ask the lender to show every payment stage.
No one can promise when rates will fall or what homes will cost at that point. Compare the homes available now using a payment you can afford without relying on a future refinance. Waiting can be sensible if the current full payment or cash needed to close exceeds your limits.
If you are comparing new and existing homes in Riverview or Ruskin, ask JB Realty to help you evaluate the properties and offer terms alongside the financing scenarios you review with your lender through our Tampa Bay buyer services.