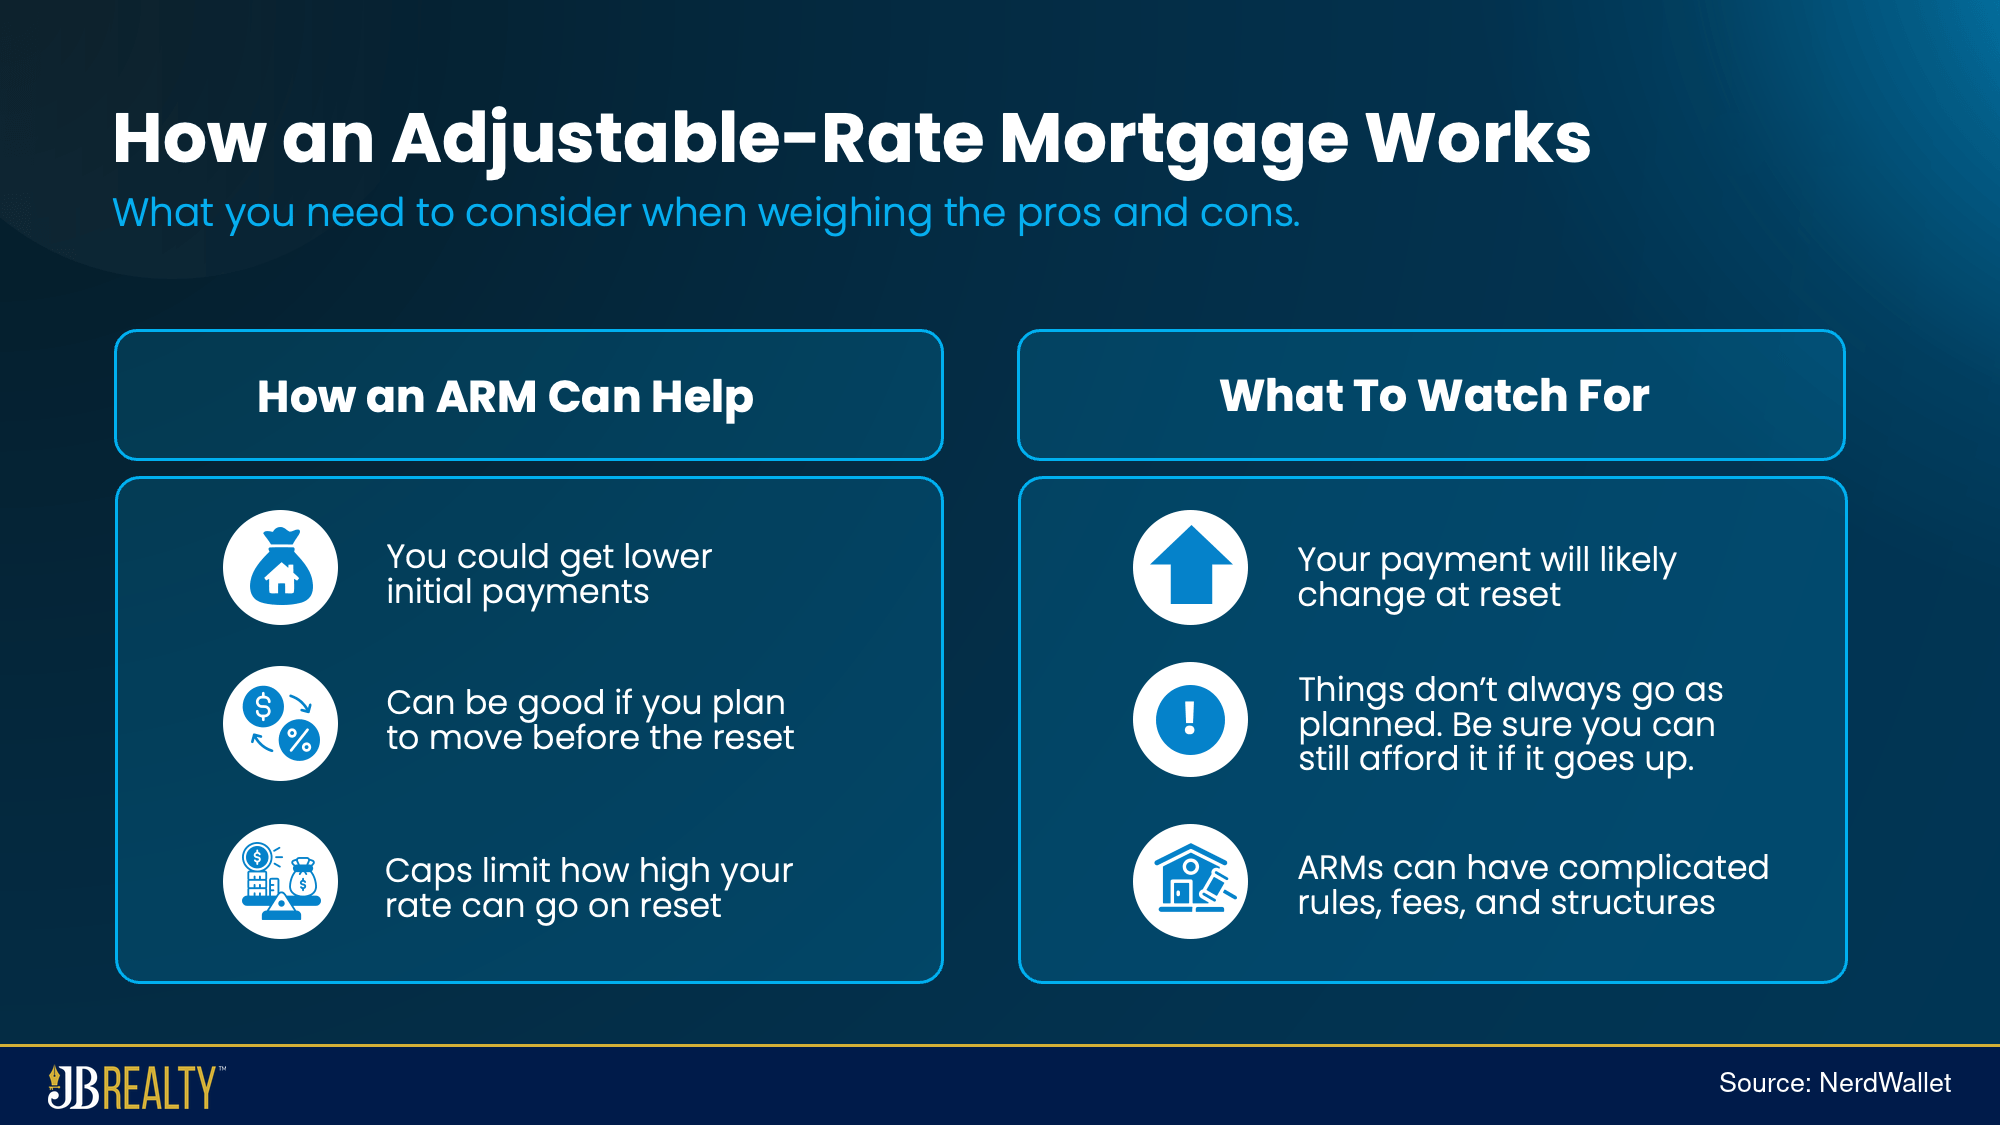
An adjustable-rate mortgage (ARM) can lower your initial payment, but it is worth considering only if you understand and can manage the later adjustments. Compare the starting savings with the possible future payment, fees, and your plans for the home. For buyers searching in Westchase, the purchase should remain workable if you stay longer than expected and cannot refinance before the rate changes.
A lower starting rate can create room in your budget. The question is how much uncertainty you would accept in exchange for that initial saving. Begin with a comfortable total housing budget, then ask a lender to compare a fixed-rate loan with the specific ARM being offered.
The mortgage payment is only part of that budget. Property taxes, homeowners insurance, and any association charges can change independently of your loan’s interest rate. Leave room for those expenses rather than treating the initial ARM payment as the maximum cost of owning the home.
An ARM may deserve consideration when the early savings are meaningful and your finances could absorb later changes. If the purchase works only at the introductory payment, a lower price or a different loan structure deserves a closer look.
The Mortgage Bankers Association’s October 21, 2026 weekly survey reported that ARMs represented 10.5% of total mortgage applications for the week ending October 16. The survey includes purchase and refinance applications, so that figure is not the share of homebuyers who closed with an ARM.

The share describes borrowing activity, not whether an ARM is suitable for your household. Actual rates, points, and fees vary with the loan and applicant. Use current written quotes rather than assuming that a national rate gap will be available on your purchase.
With a 5/1 ARM, the initial interest rate generally stays fixed for 5 years and then adjusts annually. A 5/6 ARM generally fixes the rate for 5 years and adjusts every 6 months afterward. Confirm the schedule in the loan documents because the second number does not always use the same unit of time.
After the initial period, the rate generally follows an index plus a margin, subject to the loan’s limits and other terms. The index is a market-based reference rate. The margin is the number of percentage points added to that index and is set in your agreement.
For example, an index of 4.5% plus a 2.5-percentage-point margin produces 7% before applying relevant caps, floors, and rounding rules. A floor is a minimum rate. Falling market rates therefore do not guarantee that every ARM’s payment will fall by the same amount.
The Consumer Financial Protection Bureau’s explanation of ARM rate caps distinguishes the first adjustment, subsequent adjustments, and the lifetime limit. Read all three rather than asking only whether the loan has a cap.
Consider a hypothetical 6% starting rate with a 2/2/5 cap structure for rate increases. The first adjustment could raise the rate by up to 2 percentage points, subsequent adjustments by up to 2 points each, and the lifetime maximum would be 5 points above the starting rate, or 11%. The actual rate at an adjustment would also depend on the index, margin, and contract terms.
These limits control the interest rate, not the increase in your complete housing bill. Ask your lender to calculate the first possible increase and the highest payment permitted under the actual loan terms.
Suppose a hypothetical $350,000, 30-year 5/1 ARM starts at 6%. Its monthly principal-and-interest payment would be about $2,098. After 60 scheduled payments, the remaining balance would be approximately $325,690.
If the first adjustment raised the rate to 8%, repaying that balance over the remaining 25 years would require about $2,514 per month in principal and interest. Taxes, insurance, association charges, mortgage insurance, and loan fees are excluded from these figures. This is a payment illustration, not a loan offer or a forecast.
Have the lender repeat that exercise with your actual amount, adjustment dates, and caps. Compare any early savings after accounting for differences in upfront costs. Our guide to comparing mortgage quotes explains how to keep fees and loan assumptions in the same comparison.
Refinancing requires a new loan approval and can involve closing costs. Your income, credit, debts, property value, and available loan programs may change before the first reset. Selling on a planned schedule is also uncertain.
Current lending protections do not remove that risk. For most covered mortgages, ability-to-repay requirements generally require lenders to consider and document repayment capacity rather than rely solely on a low introductory rate. Approval still does not guarantee that a higher payment will fit your future spending priorities.
Ask for a written comparison showing the starting payment, first possible adjustment, maximum payment, points and fees, and any prepayment penalty. Decide whether the loan would remain manageable without a timely refinance, a quick sale, or an assumed raise.
No. The 5 generally describes the initial fixed-rate period, not the full repayment term. After that period, the rate can adjust annually under the agreement while the loan continues over its remaining term.
Both generally begin with 5 fixed-rate years, but their later adjustment schedules differ. A 5/1 typically adjusts annually, while a 5/6 typically adjusts every 6 months. Compare the caps and other terms as well as the label.
It may, depending on the index and the agreement. A floor or other restrictions can limit decreases. Ask the lender to explain both upward and downward adjustments for the specific product.
No. You would need to qualify for the new loan under the terms available then, and refinancing can require additional cash. Choose an ARM only after considering how you would handle keeping it through an adjustment.
A standard fixed-rate loan keeps its interest rate and scheduled principal-and-interest payment stable. Taxes, insurance, or other charges can still change the total amount you pay. Compare the complete ownership budget under either loan type.
Once your lender has priced both options, we can help you focus your home search on properties that fit the payment range and cash reserves you choose.