On-time rent payments may help a lender evaluate your mortgage application, but the benefit depends on how those payments are documented and considered. Reporting rent to a credit bureau and having a lender review rent history are different processes. For St. Petersburg renters preparing to buy, the useful first step is to ask which approach fits your application before paying for a reporting service.
There are 3 separate questions: Are the payments on your credit report? Does the scoring model used for your mortgage consider that information? Can the lender assess your rental history through another underwriting process? Underwriting is the review of whether the borrower and property meet the loan’s requirements.
For eligible borrowers, Fannie Mae’s positive rent payment history feature can consider rent through its Desktop Underwriter system. When payments are absent from the credit report, the lender may obtain an authorized verification report using 12 months of bank transaction data.
Eligibility includes at least one borrower who has rented for at least 12 months, paying $300 or more monthly, and has no mortgage reported on their credit report, limited credit history, or no credit score. Your lender must confirm the applicable requirements and process. This feature can supplement the underwriting assessment without changing your credit score or automatically adding rent to your credit reports.
A reporting service sends rental payment information to one or more credit bureaus. That may help establish a record, but the result depends on the data reported and the scoring model used. A score shown in a consumer app may differ from the score used for a mortgage.
FHFA’s current credit-score policy permits lenders to use Classic FICO or VantageScore 4.0 for eligible loans sold to Fannie Mae and Freddie Mac. That does not mean every lender will use the same model for your application. Ask which model and loan program the lender is evaluating before assuming a reporting service will change the result.
Before enrolling, get clear answers to these questions:
Keep the payment trail understandable. For example, if 2 roommates split rent and one reimburses the other, ask the lender how each person’s share can be documented. Do not assume a transfer labeled “rent” will automatically satisfy the lender’s verification process.
Zillow’s analysis of 2025 mortgage data found that credit history was cited in 32.88% of denials for conventional loans used to purchase a primary home. That was the most common cited reason in the group studied.

The percentage concerns denied applications, not all people who applied. It also describes “credit history” rather than isolating applicants whose only issue was too little history. It cannot establish your personal chance of approval or show that adding rent would resolve every credit-related denial.
If you have already been declined, ask the lender to explain the specific reasons in your decision notice. A limited credit file, past payment problems, and a debt-to-income issue can require different responses. Your preparation should address the actual obstacle identified.
Review your credit reports from Equifax, Experian, and TransUnion for information that is missing, unfamiliar, or inaccurate. The Consumer Financial Protection Bureau recommends disputing errors with both the credit reporting company and the business that supplied the information, using supporting documents. Correcting an error does not guarantee a particular score increase or approval date.
Keep making required payments on time and discuss major financial changes with your lender. Opening a secured card, becoming an authorized user, closing an account, or using savings to pay off debt should be evaluated against your circumstances and buying timeline. None is a universal instruction for every renter preparing for a mortgage.
Ask for an actionable next step and a review point. That could mean verifying rental payments, resolving an inaccurate account, reducing a particular balance, or documenting income. Confirm whether a conversation or prequalification involves a credit inquiry and whether any fees apply, rather than assuming every initial review is free.
Credit is one part of mortgage readiness. Your income, debts, available cash, loan program, and the property also affect the purchase. A rent payment you manage comfortably is useful budget information, but it does not establish an affordable mortgage payment by itself.
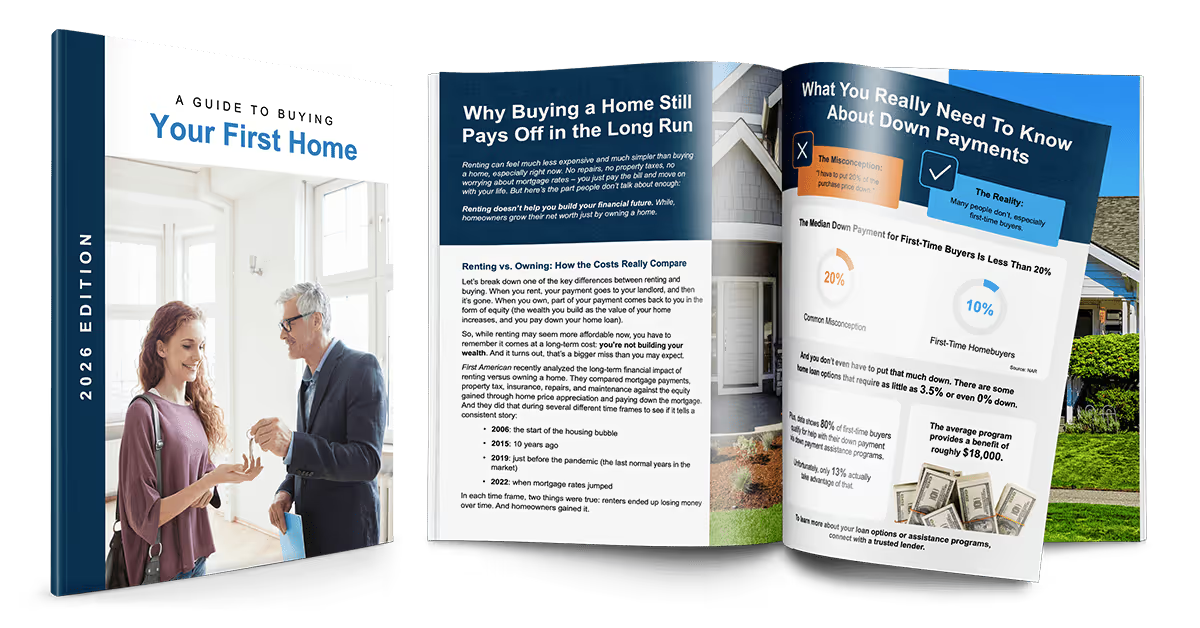
For a local home search, decide how much cash you need to close and what you want left afterward. Our article on planning a first-home purchase with less saved explains why the down payment and the complete buying budget are separate figures.
When a lender can evaluate realistic options, compare the payment, fees, and cash requirements together. Our explanation of mortgage rate quotes and preapproval can help you understand what has been reviewed and what remains conditional. Build the home search around those verified limits.
Payments do not automatically appear on every credit report or affect every scoring model. Ask your landlord or reporting provider what is submitted and where. Then ask your mortgage lender how that information would be considered for your loan.
It may. Fannie Mae’s positive rent payment history feature allows eligible borrowers’ payments to be assessed through a lender-obtained bank-data report when needed. The lender must confirm eligibility and complete the required verification; this does not guarantee approval.
A reporting service cannot establish one guaranteed outcome for every renter. Results depend on the information reported, your existing file, and the scoring model. Check whether late payments are reported and whether the model used for your mortgage considers the data.
Discuss that decision with the lender reviewing your purchase plan. A new account may be useful in some circumstances, but it can also change the information being evaluated. Ask what problem the new account would address and how it fits your application timeline.
Once your lender has clarified the financing path, we can help you plan your home search around the payment, available cash, and timing that fit your situation.